As the fourth quarter gets underway, employees across the United States enter an overlooked financial window. With only five to six bi-weekly paychecks remaining before the calendar closes, the clock is ticking on your employer retirement plan.
Unlike Individual Retirement Accounts (IRAs), where the Internal Revenue Service (IRS) allows contributions until the mid-April tax filing deadline of the following year, employer-sponsored 401(k) and 403(b) plans operate on a strict December 31 cutoff. Once your final payroll run processes at year-end, your contribution window for that tax year closes permanently.
Learning how to strategically max out 401k 2026 tax bill liabilities before late December does more than prepare you for retirement—it delivers an immediate, substantial reduction in your current-year taxable income.
Here is how the contribution ceilings work, the latest SECURE 2.0 rules, the exact paycheck math required, and how to capture every dollar of your employer match.
1. Statutory Contribution Limits: Employee, Employer, and Catch-Up Caps
Retirement limits adjust periodically to reflect prevailing inflation benchmarks. To execute a successful year-end sprint, ensure you are anchoring your payroll deferrals to the correct statutory limits.
Add an infographic summarizing the baseline employee limit of $24,500, standard catch-up of $8,000, and SECURE 2.0 super catch-up of $11,250 here]
Key Numbers to Remember:
- Elective Employee Deferral Limit: $24,500 (This applies across all Traditional pre-tax and Roth elective deferrals combined).
- Overall Defined Contribution Limit (Section 415(c)): $72,000 (This accounts for employee elective deferrals, mandatory employer matching, non-elective profit sharing, and voluntary after-tax contributions).
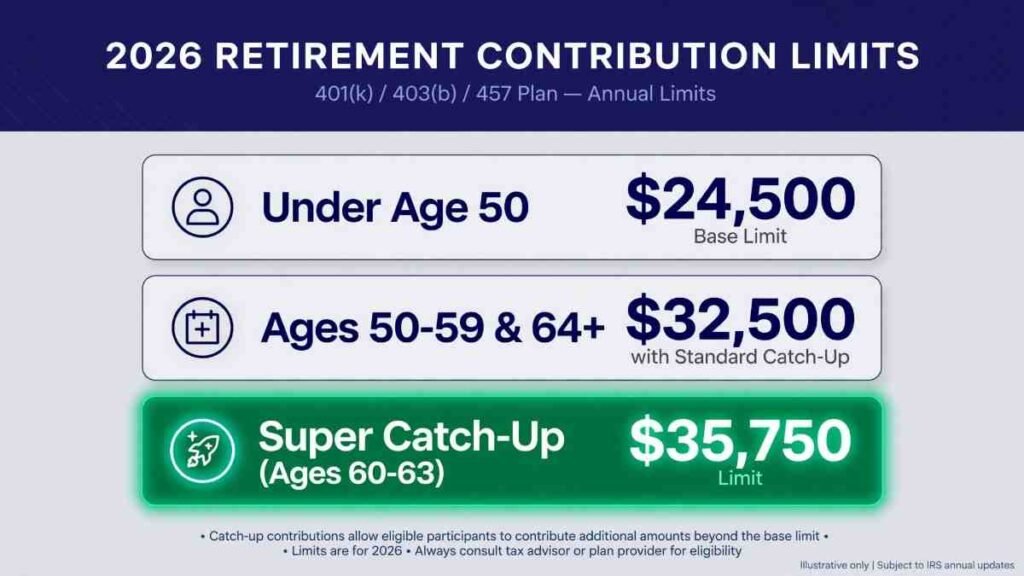
- Standard Catch-Up Contribution (Ages 50 and Older): $8,000 (Allowing individuals aged 50+ to contribute up to $32,500 in elective salary deferrals).
Understanding these distinctions prevents over-contributions that trigger complex payroll reversals or penalty excise taxes.
To examine how regular compound contributions build portfolio balances across 10, 20, or 30 years, simulate your figures on the CalcNest SIP & Compounding Calculator.
2. The SECURE 2.0 “Super Catch-Up”: What Workers Aged 60 to 63 Must Know
The SECURE 2.0 Act introduced a major rule change for near-retirees: the Enhanced Super Catch-Up Contribution.
Historically, catch-up contributions applied universally to anyone age 50 or older. Under the enhanced framework, individuals who attain ages 60, 61, 62, or 63 during the calendar year qualify for a significantly expanded catch-up ceiling.
| Category / Contributor Age Bracket | Standard Base Limit | Catch-Up Allowance | Total Annual Deferral Ceiling |
|---|---|---|---|
| Standard Contributor (Under Age 50) | $24,500 | $0 | $24,500 |
| Standard Catch-Up (Ages 50–59 & 64+) | $24,500 | $8,000 | $32,500 |
| Super Catch-Up (Ages 60, 61, 62, 63) | $24,500 | $11,250 | $35,750 |
If you fall into that four-year window between ages 60 and 63, you can shelter up to $35,750 of pre-tax earnings.
For someone in the 24% or 32% marginal federal tax bracket (plus state income taxes), sheltering that much income yields thousands of dollars in direct, upfront tax savings.
3. The Year-End Paycheck Math: How to Recalibrate Your Deferrals
Most payroll systems let you designate 401(k) contributions as either a flat dollar sum or an exact percentage of gross earnings.
If you have coasted along at a standard 5% or 6% deferral rate all year, your year-to-date (YTD) contributions may fall well short of the $24,500 cap.
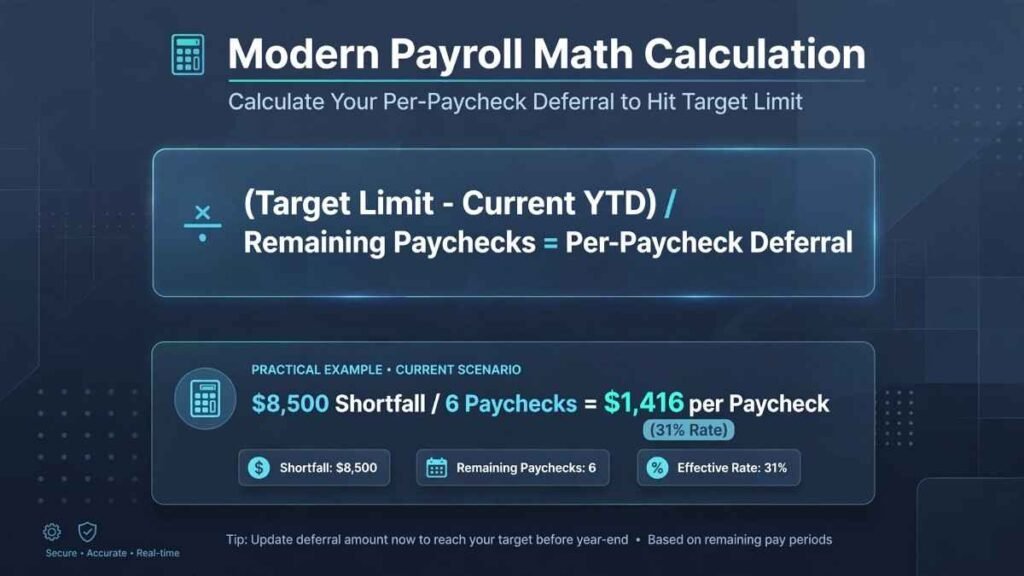
Add a calculation visual showing the formula: (Cap minus YTD contributions) divided by remaining paychecks = Required Deferral per Paycheck]
The Basic Paycheck Formula:
Required Deferral per Paycheck = (Target Cap – Current YTD Contributions) / Remaining Paychecks in Year
Practical Walkthrough: The Bi-Weekly Earner
Let’s review an actual employee scenario:
- Annual Gross Salary: $120,000 ($4,615 gross per bi-weekly pay period)
- Target Employee Contribution: $24,500
- Contributions Made Through September: $16,000
- Remaining Shortfall: $8,500 ($24,500 – $16,000)
- Remaining Paychecks in the Year: 6 pay periods
Step 1: Dollar Allocation
$8,500÷6 pay periods=$1,416.67 per paycheck
Step 2: Percentage Allocation
$4,615 gross paycheck$1,416.67≈30.7% deferral rate
To capture the remaining room under the cap, this employee must log into their benefits portal (e.g., Fidelity, Vanguard, Empower) and increase their deferral election from a modest rate up to 31% across the final six payroll cycles.
4. Immediate Tax Relief: Federal Bracket Savings Compared
Contributing to a Traditional 401(k) reduces your gross adjusted income dollar-for-dollar in Box 1 of your Form W-2.
The table below shows the direct federal tax savings when channeling an additional $6,000 to $10,000 into a pre-tax 401(k) before the final payroll run of the year:
| Marginal Federal Tax Bracket | Additional $6,000 Pre-Tax Deferral | Additional $10,000 Pre-Tax Deferral | Effective Take-Home Cash Impact (Per $10k Deferred) |
|---|---|---|---|
| 12% Federal Bracket | Saves $720 | Saves $1,200 | Costs $8,800 in net pay |
| 22% Federal Bracket | Saves $1,320 | Saves $2,200 | Costs $7,800 in net pay |
| 24% Federal Bracket | Saves $1,440 | Saves $2,400 | Costs $7,600 in net pay |
| 32% Federal Bracket | Saves $1,920 | Saves $3,200 | Costs $6,800 in net pay |
| 35% Federal Bracket | Saves $2,100 | Saves $3,500 | Costs $6,500 in net pay |
(Note: These figures exclude state and local income tax reductions, which boost overall tax savings even higher for residents in states like California, New York, or New Jersey).
For individuals on the edge of a higher tax bracket, aggressive year-end contributions can keep total adjusted gross income below thresholds that trigger phaseouts for child tax credits, clean vehicle credits, or higher Medicare premium surcharges (IRMAA).
To determine how saving on direct liabilities frees up cash flow to pay off long-term debts, test your repayment options on the CalcNest Loan Amortization Calculator.
5. The Critical Employer Match Trap: Understand “True-Up” Provisions
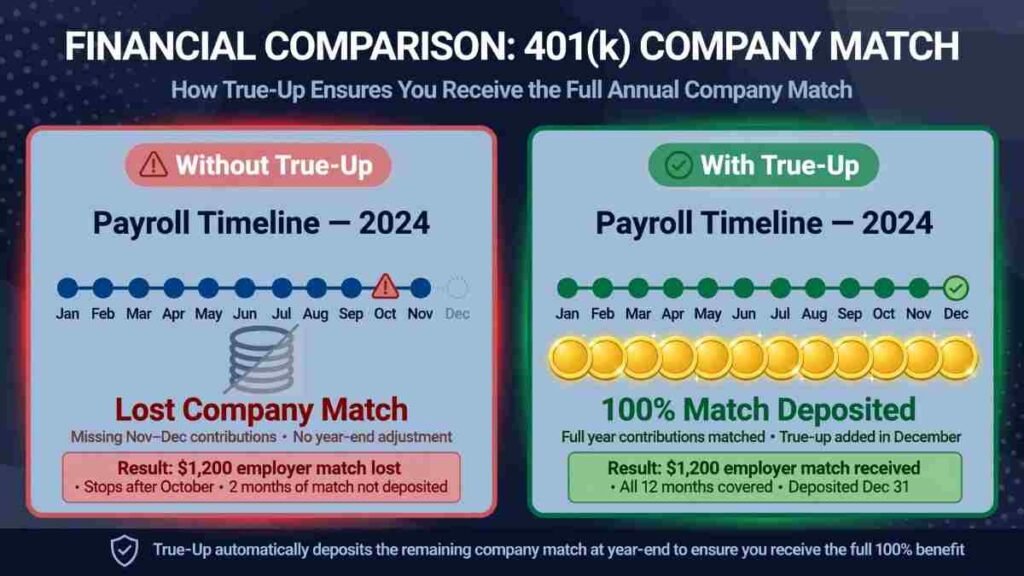
One common pitfall when racing to hit the annual limit is front-loading contributions too quickly and missing out on your employer’s match.
Many employers match contributions on a per-paycheck basis (e.g., 50% match on contributions up to 6% of your salary each pay period). If you increase your deferral to 50% or 60% and hit the $24,500 cap in early November, you cannot contribute during December payroll runs.
Add a comparison visual showing Per-Paycheck Match with a True-Up vs Per-Paycheck Match without a True-Up]
Scenario A: Your Plan Has a “True-Up” Provision
Your employer’s retirement system reviews your annual compensation retrospectively in early spring. If you maxed out early, the automated true-up calculates the full match you were entitled to and deposits the missing funds directly into your account.
Scenario B: Your Plan Does NOT Have a True-Up Provision
If your employer lacks a true-up provision, any pay period in which you contribute 0% (because you hit the cap early) receives zero employer match. In this setup, you leave free company contributions on the table.
The Action Step: Before setting your payroll deferral rate higher, review your summary plan description (SPD) or email your HR benefits department to ask: “Does our 401(k) plan include an annual match true-up provision?”
If it does not, calculate your contributions to hit the $24,500 limit on your final paycheck of the year, rather than reaching it early.
6. Traditional vs. Roth 401(k): Where Should Year-End Dollars Go?
When adjusting your late-year contributions, determine whether those deferrals should flow into a pre-tax Traditional account or an after-tax Roth account.
| Strategic Dimension | Traditional Pre-Tax 401(k) | Designated Roth 401(k) |
|---|---|---|
| Tax Impact This Year | Immediate deduction; lowers taxable W-2 income | Zero upfront deduction; funded with after-tax pay |
| Tax Impact at Retirement | Distributions taxed as ordinary income | Qualified withdrawals are 100% tax-free |
| Ideal Profile | High current earners in peak marginal tax brackets | Early-career or individuals anticipating higher future taxes |
| RMD Requirements | Required Minimum Distributions apply at 73/75 | No lifetime RMDs (aligned with Roth IRA treatment) |
If lowering this year’s tax liability is your primary focus, directing late-year contributions into a pre-tax Traditional 401(k) provides immediate tax relief.
Conversely, if you expect tax rates to climb significantly or value tax-free withdrawals in retirement, splitting or pivoting contributions toward a Roth 401(k) builds valuable tax diversity.
Action Checklist: What to Do This Week
| Timeline | Action Step |
|---|---|
| Immediate (Day 1) | Log into your retirement portal and pull your current year-to-date (YTD) contributions |
| Day 2 | Subtract YTD contributions from $24,500 (or $32,500 / $35,750 for catch-up brackets) |
| Day 3 | Divide by remaining pay periods to determine your required per-paycheck percentage |
| Day 4 | Confirm whether your company plan provides an annual employer match true-up |
| Day 5 | Submit your updated payroll deferral election before the upcoming payroll cutoff |
Finish the Year with a Built-in Tax Advantage
Maximizing your retirement plan is one of the most effective ways to lower your taxes and build long-term wealth. When you max out 401k 2026 tax bill contributions, you convert money that would otherwise go toward federal taxes into a compounding investment working for your future.
Log into your benefits portal, calculate your remaining paychecks, and update your deferral elections before the year-end payroll processing deadline passes.
What is your approach? Are you pushing to hit the maximum employee limit this year, or balancing your retirement contributions with other financial goals?
Share your questions and strategies in the comments below! To calculate your investment growth, mortgage schedules, and multi-year wealth plans, explore the free interactive tools across the CalcNest Platform.