Meta Description: Confused between SIP and Lump Sum mutual fund investments? Read our comprehensive 2026 guide comparing returns, market risks, and strategies to build long-term wealth for global and Indian investors.
When it comes to building long-term wealth, mutual funds have emerged as one of the most powerful financial instruments for modern investors. Whether you are an individual earning in INR within India or part of the global diaspora looking to manage cross-border or domestic wealth, one fundamental question constantly arises: “Should I invest through a Systematic Investment Plan (SIP) or put in a lump sum amount all at once?”
Choosing between SIP and lump sum investing can significantly impact your portfolio’s performance, especially given market fluctuations. In this detailed guide, we will break down both investment styles, analyze their pros and cons, look at how they perform in different market conditions, and help you decide which approach aligns best with your financial goals.
Understanding the Core Concepts
Before comparing their returns, it is essential to understand how both investment mechanisms actually function.
What is a Systematic Investment Plan (SIP)?
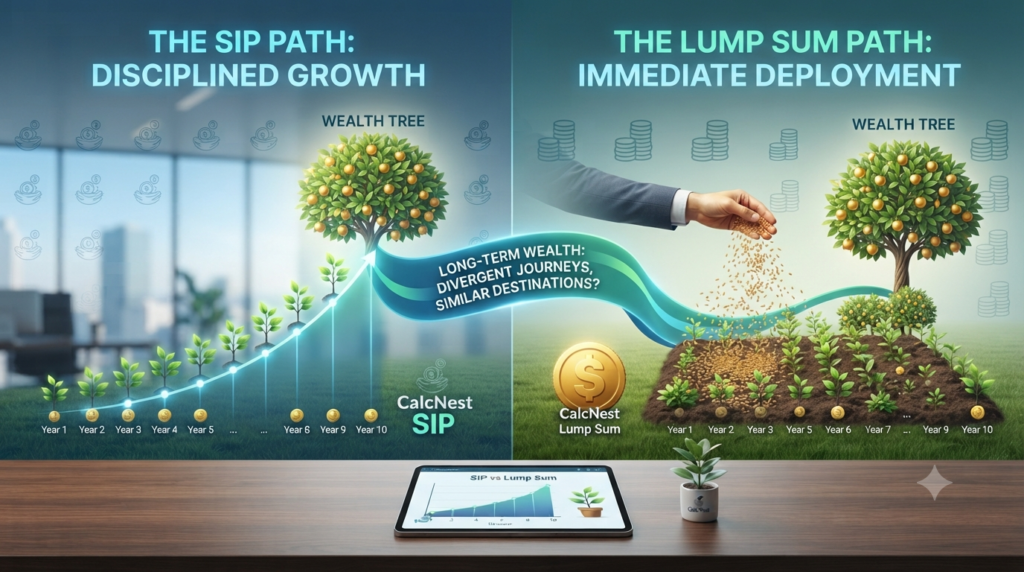
A Systematic Investment Plan (SIP) allows you to invest a fixed amount of money in a mutual fund scheme at regular intervals—such as weekly, monthly, or quarterly. Think of it as a disciplined recurring deposit, but linked to equity or debt markets.
- Rupee Cost Averaging: When the market is down, your fixed SIP amount buys more units of the mutual fund. When the market is up, it buys fewer units. Over time, this averages out your purchase cost and eliminates the need to time the market.
- Financial Discipline: SIPs automate your savings, cultivating a healthy long-term habit of regular investing without straining your monthly budget.
- Low Entry Barrier: You can start a mutual fund SIP with nominal amounts, making it ideal for young professionals and regular wage earners.
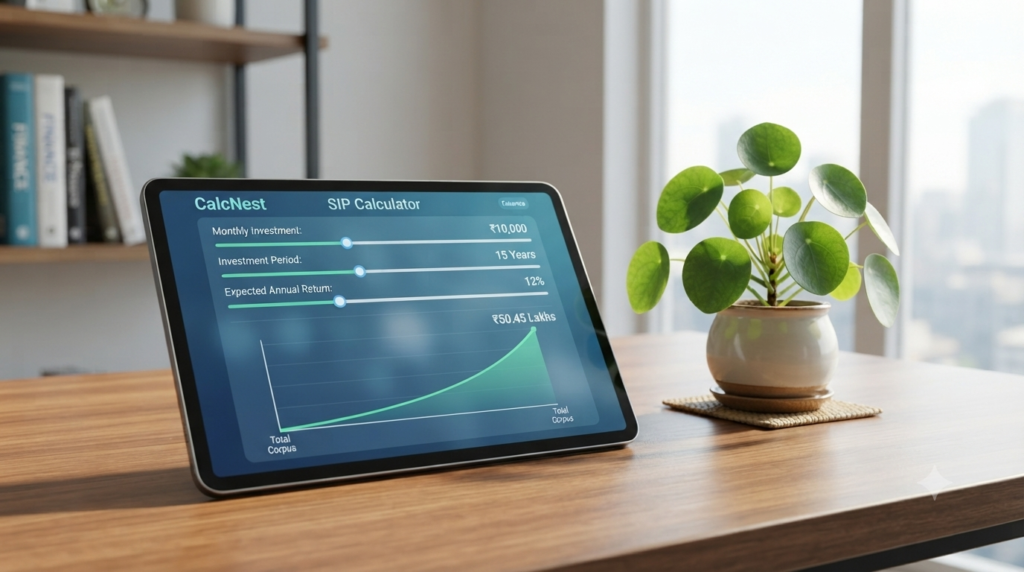
Pro Tool: If you want to forecast your potential wealth accumulation using monthly contributions, check out the CalcNest SIP Calculator for instant and accurate estimates.
What is a Lump Sum Investment?
A Lump Sum Investment involves investing a large, single sum of money—such as an annual bonus, an inheritance, or proceeds from selling an asset—into a mutual fund all at once.
- Maximized Time in Market: Your entire capital starts working for you from day one. In a steadily rising bull market, lump sum investments typically outpace SIPs because all your money is compounding immediately.
- Capitalizing on Market Corrections: If you deploy a lump sum during a major market crash or correction when valuations are low, your long-term gains can be extraordinary.
SIP vs Lump Sum: Key Differences at a Glance
| Feature | Systematic Investment Plan (SIP) | Lump Sum Investment |
| Capital Requirement | Small, periodic installments (monthly/weekly) | Large, single payment |
| Market Risk Handling | Lower risk due to rupee cost averaging | Higher risk due to entry timing vulnerability |
| Ideal Investor Profile | Salaried employees, regular income earners | Business owners, individuals with sudden cash windfalls |
| Market Timing | No market timing required | Requires astute market valuation analysis |
| Psychological Stress | Low; automated and emotion-free | High; vulnerable to immediate market drops |
Deep Dive: Which Strategy Delivers Better Long-Term Returns?
Financial research and historical market data show that neither strategy is universally “better” than the other; rather, their effectiveness depends entirely on market cycles and cash flow availability.
1. When Does SIP Win?
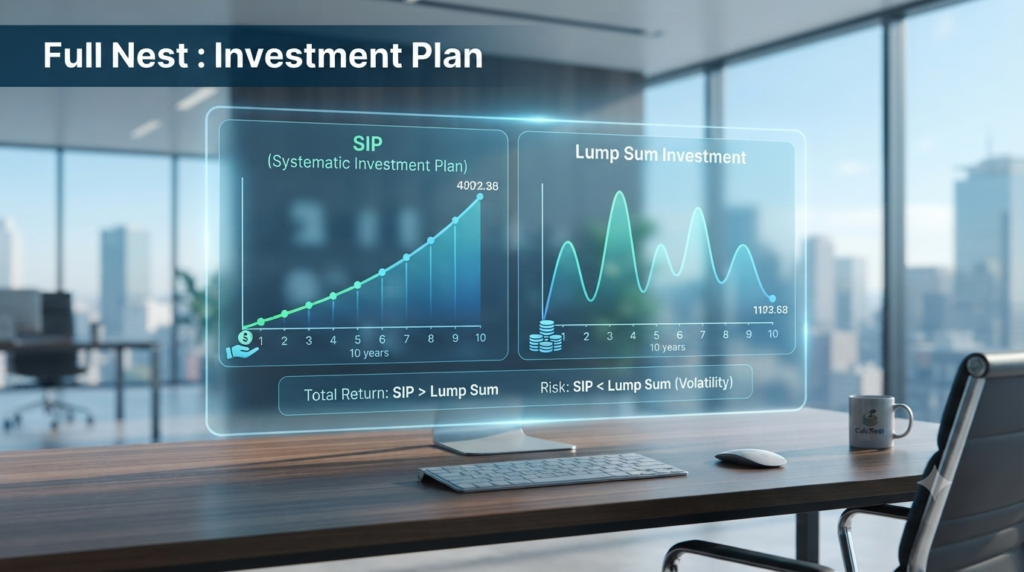
SIPs generally win in terms of consistency and risk mitigation. Because global and domestic stock markets experience regular bouts of volatility, trying to time the entry point can lead to severe losses. SIP protects you from your own emotional impulses (fear and greed).
If you are saving for long-term objectives like retirement or children’s education, regular investors should maintain steady contributions. To ensure your financial practices align with regulatory standards, you can review consumer guidelines provided by regulatory bodies like the Securities and Exchange Board of India (SEBI) for domestic retail investors.
2. When Does Lump Sum Win?
Lump sum investments tend to outperform SIPs during a secular bull market—a prolonged upward market trend. Since equities generally trend upward over long horizons (5 to 10+ years), getting your money into the market sooner rather than later historically yields higher absolute returns.
However, deploying a large sum requires monitoring broader macroeconomic conditions. For global financial analysis, tracking market sentiment on platforms like Bloomberg Markets can offer valuable insights into global liquidity and asset valuations.
Hybrid Strategy: Can You Use Both?
Many sophisticated investors do not choose just one; instead, they adopt a hybrid approach:
- Maintain a core SIP structure funded by monthly income to build long-term discipline.
- Keep emergency cash or unexpected financial windfalls liquid until market corrections occur, then deploy them as Lump Sum tranches or via a Systematic Transfer Plan (STP).
To explore other financial metrics and plan your overall wealth blueprint, feel free to navigate back to the main CalcNest Home Page and try out our range of specialized calculators.
Frequently Asked Questions (People Also Ask)
Q1. Can I pause, modify, or stop my mutual fund SIP anytime?
Ans: Yes. Open-ended mutual fund SIPs carry no lock-in period (except for tax-saving ELSS funds, which have a statutory 3-year lock-in). You can pause, increase, decrease, or completely stop your SIP online through your investment platform at zero penalty.
Q2. Is a Lump Sum investment riskier than a SIP?
Ans: Yes, lump sum investments carry higher timing risk. If you invest a large amount right at an all-time market peak and a correction follows, your portfolio will immediately show negative returns. SIP spreads this risk across different market cycles.
Q3. What is an STP, and how is it related to Lump Sum?
Ans: A Systematic Transfer Plan (STP) is a strategy where you park a lump sum amount into a liquid or low-risk debt fund and periodically transfer a fixed amount into an equity mutual fund. It combines the benefits of a lump sum deployment with the safety of rupee cost averaging.
Q4. Which option is better for tax planning in India or the US?
Ans: For tax-saving purposes, specific categories like Equity-Linked Savings Schemes (ELSS) in India allow both SIP and lump sum options, with each installment locked for 3 years under Section 80C. For US-based accounts, tax-advantaged vehicles like IRAs or 401(k)s operate on distinct contribution rules. Always consult a tax professional for regional compliance.
Disclaimer
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial, legal, or investment advice. Mutual fund investments are subject to market risks; read all scheme-related documents carefully before investing. Past performance is not indicative of future returns. Always evaluate your risk tolerance or consult a certified financial advisor before making major investment decisions.